How a Recontribution Strategy Can Reduce Tax on Your Super for Future Generations

Rancie Financial • August 27, 2025

Share this article

How a Recontribution Strategy Can Reduce Tax on Your Super for Future Generations

Did you know your adult children could pay up to 17% tax on your super if they inherit it? A recontribution strategy can help reduce, or even eliminate, this tax, allowing you to leave more of   your wealth to your family.

A recontribution strategy works by withdrawing a lump sum from your super (once you meet a condition of release, typically aged 65+ or retired) and then recontributing it back as a non-concessional (after-tax) contribution. This converts part of your taxable component into tax-free   dollars, which can make a significant difference if your super is eventually passed to adult children or other non-dependant beneficiaries. While super left to a spouse or dependent children under 18 is generally tax-free, adult children can face up to 17% tax on the taxable portion of your balance. A recontribution strategy can help reduce this tax, keeping more of your super in your family’s hands.

Here’s an example of how it works:

Before Strategy

  • John, 65, single, has $600,000 in super, all taxable.
  • If John passes away, his adult child could pay around $102,000 in tax  (600k × 17%).

After Strategy

  • John withdraws $360,000 and recontributes it using the bring-forward rule.
  • His super remains $600,000, but 60% is now tax-free.
  • If John passes away, only $240,000 would be taxable, and the tax bill drops to ~$40,800.

Tax Saved:   ~$61,200

Beneficiary Before Recontribution After Recontribution
Adult Child (Non-dependant) $600k taxable → Tax  $102,000 $240k taxable → Tax  $40,800

If John had a spouse, his super would generally pass to them tax-free, regardless of the taxable or tax-free componen

A recontribution strategy can be a simple yet powerful way to reduce tax on inherited super, convert more of your balance into tax-free dollars, and help you   leave more money for your loved ones. If you’d like to explore how this strategy could benefit you or someone you know, speak with one of our advisers today.

This article provides general information only and does not take into account your personal circumstances. You should seek personalised financial advice before making any decisions.

Recent Posts

By Rancie Financial • July 29, 2026
With the 2026 financial year now complete, investors can reflect on a year that highlighted how quickly economic conditions, government policy and investment markets can change.
By Rancie Financial • March 25, 2026
Most of the time share markets are relatively calm, but periodically they tumble and generate headlines like “billions wiped off share market.”
By Rancie Financial • March 15, 2026
Oil and investment markets initially reacted relatively calmly to the US/Israel war with Iran, despite the Strait of Hormuz through which 20-25% of global oil and gas supplies flow through on a daily basis being closed from the get go.
By Rancie Financial • February 6, 2026
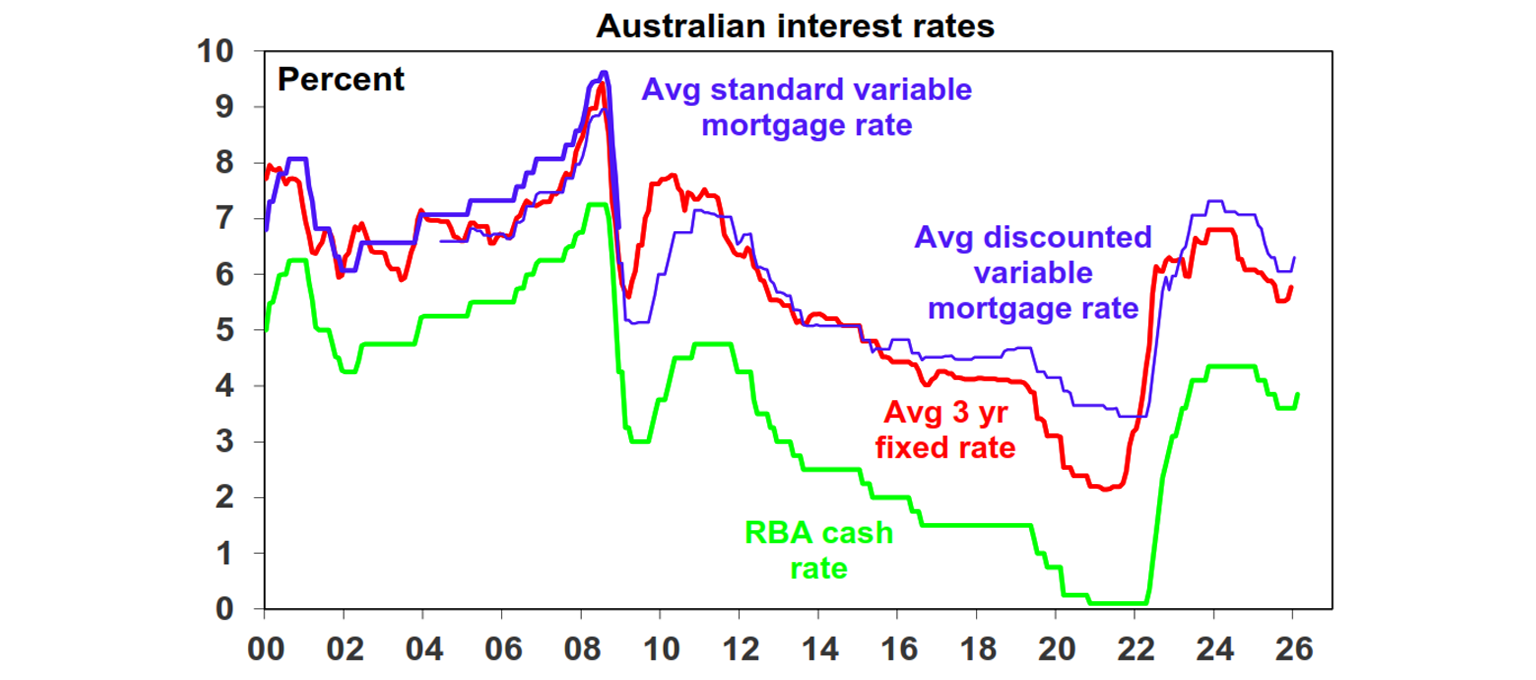
The RBA’s decision to hike rates to 3.85% was no surprise with it being about 70% factored in by the money market and 22 of the 28 economists surveyed by Bloomberg expecting a hike.
By Rancie Financial • January 28, 2026
Many investors breathed a sigh of relief at having survived (and even thrived) the turbulent economic and political events of 2025.
By Rancie Financial • December 18, 2025
Investing in rare earths requires patience and perspective. Few investment sectors combine geopolitical intrigue, technological innovation and long-term growth potential quite like rare earth elements (REEs).
By Rancie Financial • November 12, 2025
Bringing your family into estate planning conversations can be one of the most valuable steps toward clarity and peace of mind.
By Rancie Financial • October 12, 2025
For Australians aged 55 and over, selling the family home can also be a chance to boost retirement savings.
By Rancie Financial • September 17, 2025
“Will this be enough to fund our retirement?”
By Rancie Financial • August 11, 2025
Catch-up contributions allow you to exceed the standard annual concessional cap ($30,000 pa) provided your total super balance was under $500,000 at the previous 30 June and you have unused cap amounts from the past five financial years.
Show More